

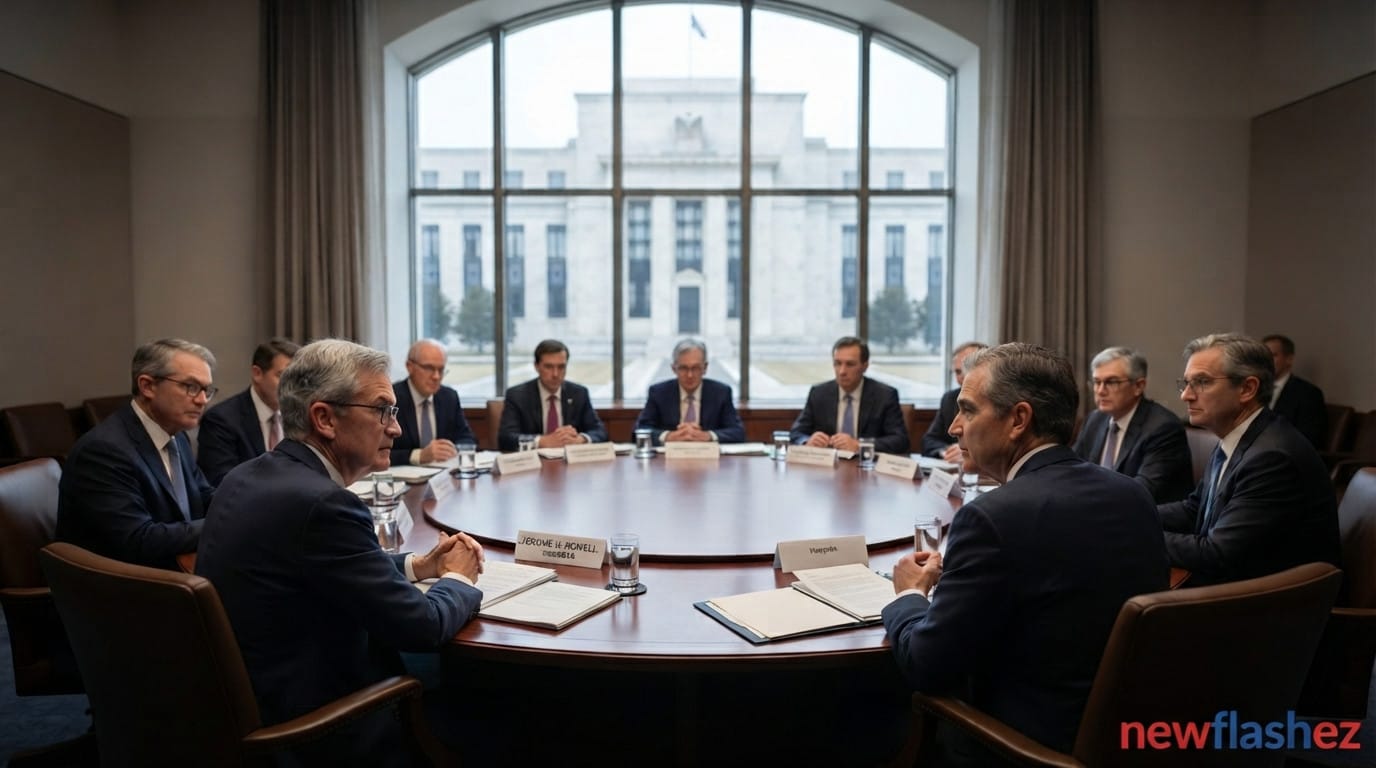
Federal Reserve Interest Rates: FOMC Convenes Amid Sticky Inflation and Labor Market Resilience
As global financial markets brace for a pivotal shift in global monetary policy, Federal Reserve interest rates have once again taken center stage on Wall Street. According to recent reports from leading financial publications, including The Wall Street Journal, the Federal Open Market Committee (FOMC) has officially kicked off its high-stakes monetary policy meeting. Investors, institutional traders, and corporate executives are scrutinizing every word and data point emanating from Eccles Building as policymakers weigh whether to maintain elevated borrowing costs or pivot in response to persistent economic pressures.
The central bank’s overarching dilemma stems from a complex macroeconomic landscape where Federal Reserve interest rates must balance the fight against stubborn inflation with the remarkable durability of the American labor market. While monetary authorities initially anticipated a smoother descent toward price stability, recent economic indicators demonstrate that underlying inflationary pressures remain stubbornly above the central bank’s official 2% target.
The Macroeconomic Backdrop – Inflation Versus Labor Strength
To fully comprehend the gravity of the current FOMC deliberations, market participants must examine the dual forces driving current Federal Reserve interest rates policy: persistent consumer price inflation and an exceptionally robust job market.
For months, Wall Street analysts have debated the timing and magnitude of potential monetary easing. However, incoming economic data has consistently complicated these projections. The labor market continues to defy expectations of a broad cooldown, posting strong job gains and maintaining low unemployment rates. This labor resilience provides consumers with sustained purchasing power, which in turn feeds into ongoing service sector inflation.
- Core Inflation Metric: Consumer and producer price indices continue to print above the Federal Reserve’s stated 2% medium-term target.
- Labor Market Resilience: Nonfarm payroll expansions and steady wage growth have prevented the sharp economic slowdown that some economists previously projected.
- Borrowing Costs: Current Federal Reserve interest rates sit at restrictive multi-decade highs, exerting intense pressure on real estate, manufacturing, and leveraged corporate debt.
As highlighted in reports by major financial desks, the persistence of these metrics leaves little room for premature celebration among policymakers, reinforcing the argument that Federal Reserve interest rates may need to remain restrictive for an extended duration.
Market Expectations and the Policy Dilemma
Financial institutions across New York and international financial hubs are aggressively repositioning their portfolios as they digest the implications of sustained Federal Reserve interest rates. Bond yields have experienced heightened volatility, and equity indices—particularly technology and growth sectors—have shown sensitivity to shifting rate expectations.
The core question facing the FOMC is no longer just when easing might begin, but whether additional tightening or a prolonged plateau is necessary to anchor long-term inflation expectations.

Market strategists note that maintaining high Federal Reserve interest rates carries distinct risks. While it successfully curbs runaway price spikes, it simultaneously increases debt-servicing burdens for small businesses, commercial real estate developers, and regional banking institutions. Conversely, loosening monetary policy too early risks reigniting inflationary spirals reminiscent of previous decades.
Sector-Specific Vulnerabilities and Capital Allocation
The ongoing debate surrounding Federal Reserve interest rates is transmitting uneven shockwaves across various sectors of the U.S. economy:
- Banking and Financial Services: Net interest margins remain a focal point as institutions navigate higher funding costs and shifting deposit betas.
- Technology and Growth Equities: High valuations face downward pressure whenever rate-cut timelines are pushed further into the future, as higher discount rates reduce the present value of future cash flows.
- Real Estate and Construction: Residential and commercial property markets continue to operate under a constrained credit environment, directly linked to prevailing Federal Reserve interest rates.
Corporate treasurers and institutional investors are increasingly focusing on balance sheet strength, prioritizing cash generation and low debt-to-equity ratios to insulate themselves against prolonged monetary tightening.
Strategic Outlook for Investors and Market Participants
Navigating an environment shaped by elevated Federal Reserve interest rates requires a disciplined, data-dependent investment strategy. As the FOMC finalizes its policy statement and economic projections, market participants should monitor key forward-looking indicators:
- The Dot Plot: Changes in individual Fed officials’ rate projections for the remainder of the year and into the medium term.
- Chairman Press Conference Tone: Subtle shifts in rhetoric regarding labor market balance and inflation risks.
- Incoming Macro Data: Monthly employment reports, Retail Sales figures, and Personal Consumption Expenditures (PCE) print releases.
Ultimately, the decisions made during this critical policy meeting will establish the macroeconomic baseline for corporate earnings, credit availability, and asset valuations for quarters to come. Stay tuned to Newflashez for live updates and in-depth economic analysis as developments unfold.
For more economic reports, visit the newflashez Business & Markets Section.
